-
2026/10/23 08:53
Crypto donations: how charitable organisations can accept Bitcoin, Ethereum and other tokens
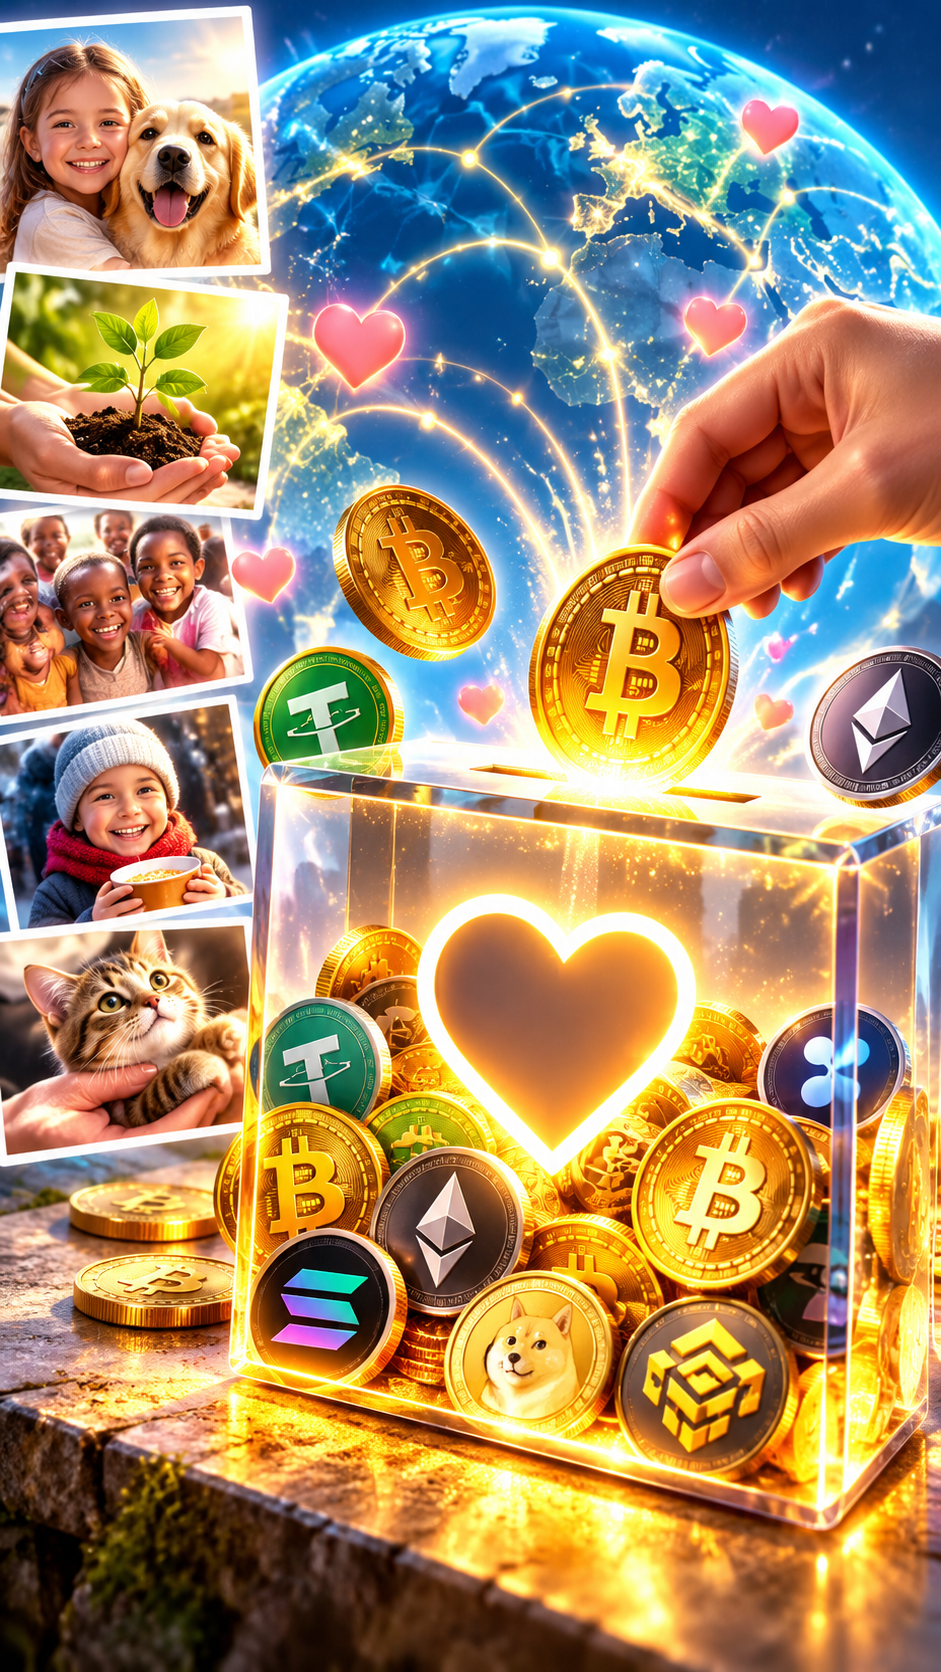
Charitable donations in Bitcoin, Ethereum, stablecoins and other crypto-assets are no longer a novelty for philanthropists in Europe. In the Netherlands, Germany and France, charitable organisations already have – and are continuing to set up – dedicated channels for crypto donations, whilst international foundations allow digital assets to be transferred either directly or via specialised platforms. For a benefactor, this is always convenient. For a charity, it represents yet another global channel for raising funds. However, it is important to note that a cryptocurrency donation is not simply a QR code containing a Bitcoin address.
Crypto philanthropy: benefits, challenges, and donor identification
Blockchain makes it possible to track cross-border asset movements in a public ledger, but the claim that such payments are always free or guaranteed to be faster than bank transfers is incorrect a priori. After all, the fee depends on the specific network, network congestion and the conversion method.
Does the transparency of blockchain allow for automatic donor identification? Public blockchains such as Bitcoin and Ethereum allow on-chain fund movements to be verified, but the address itself does not reveal the identity of its owner. Furthermore, certain technologies can reduce the transparency of transactions. Consequently, blockchain transparency does not equate to the automatic identification of a donor. A wallet address may be visible, but the owner’s name may not be.
There is no single, specific regulatory framework within the European Union specifically for ‘cryptocurrency donations’. Consequently, an organisation accepting donations must simultaneously take into account national legislation, tax rules, AML/CFT requirements, the GDPR and regulations governing crypto services.
Crypto transactions and charity in the EU
If an organisation uses a third-party service to exchange, store or transfer crypto-assets, it must always verify the service’s status and compliance with European requirements. The mere fact that a charitable organisation receives a crypto donation does not automatically make it a CASP under MiCA. Regulatory requirements may arise depending on the specific crypto services the organisation actually provides.
A charity may accept BTC or ETH via a specialised provider, automatically convert the asset into euros and receive fiat currency. In this way, the organisation reduces the risk of exchange rate fluctuations, as Bitcoin can rise or fall by tens of per cent over a relatively short period. If a fund receives 100,000 euros in BTC and then decides to spend these funds a month later, its actual available budget may already differ significantly from the original amount. Therefore, a ‘receive and convert immediately’ policy is, for most charitable organisations, considerably simpler than attempting to profit from volatility.Spain: Crypto donations are not tax-exempt
In Spain, it is essential to distinguish very carefully between three things: the actual transfer of the crypto asset, the tax implications for the donor, and the tax status of the recipient.
In Spain, the tax treatment of a crypto donation depends on the recipient’s status and the specific transaction. For donations made to organisations specified by law, the capital gain realised by the donor may be exempt from tax.
For an individual, the transfer of a crypto-asset may have tax implications. Therefore, a Spanish benefactor should not assume that ‘because it is a donation, there are no taxes’. For a substantial contribution, prior consultation is required, along with documentation of the market value of the crypto-asset at the time of the transaction.
France: crypto-donations as a practical tool for charitable contributions
French associations have long accepted crypto-assets and can issue tax documents provided the donor is identified and the value of the contribution is correctly determined. A donor wishing to obtain confirmation for tax purposes must be prepared to provide the necessary details.
The French tax authority emphasises that donations may entitle the donor to a tax deduction, particularly for eligible organisations, and has a procedure in place for issuing receipts. However, the official French receipt does not contain a specific field for crypto-assets, which is why the tax treatment of crypto donations remains legally ambiguous.
Germany: Crypto donations in Bitcoin and Ethereum
German non-profit organisations also accept crypto donations. For example, certain foundations accept BTC and ETH directly. A foundation may use cryptocurrency solely as a modern channel for raising funds. Some of them offer donors the option of receiving a written confirmation upon providing their name, address, the amount donated and the transaction ID.
The Netherlands: the relationship between donor and recipient
In the Netherlands, tax rules depend on the organisation’s status, the nature of the contribution and the relationship between the donor and the recipient.
Tax relief depends on ANBI status and compliance with the stipulated conditions; for crypto donations, the procedure for valuing and documenting the asset must be checked separately.
Ukraine: modern technology works, but legislation is lagging behind
Ukraine’s experience with crypto donations has become one of the most notable in the world since the start of the full-scale war. However, as of 2026, the legal situation remains more complex than it might appear.
Law No. 2074-IX ‘On Virtual Assets’, adopted in 2022, has not yet come into force. This is precisely why it cannot be said that Ukraine already has a fully-fledged specialised market for virtual assets based on the MiCA model.
As a result, Ukrainian funds must pay particular attention to accounting, foreign exchange, tax, AML and banking aspects. An additional risk is sanctions-related restrictions.
DAC8 and AML
From 1 January 2026, DAC8 – a system of tax transparency for transactions involving crypto-assets – will come into force in the EU, meaning that crypto donations are becoming increasingly ‘visible’.
Crypto service providers must collect and pass on the relevant information to the tax authorities, which is a major advantage for a charitable foundation. A transparent system reduces the risk of money laundering allegations and allows donors to verify the origin and movement of funds.
The charity must know where the money was transferred from, and the most dangerous mistake is to assume that charitable status automatically legitimises any crypto donation.
If a foundation receives a substantial donation, it must have a procedure in place to verify the donor and the source of the funds. Particular attention must be paid to funds that may be linked to sanctions, fraud, the dark web or other criminal activity.
Checklist: 10 rules for crypto donations to a foundation in the EU
1. Determine the foundation’s legal status in the relevant country.
2. Check which crypto assets are permitted to be accepted.
3. Determine the source of the exchange rate and the valuation date of the donation.
4. Check the CASP if the foundation uses a third-party provider.
5. Take into account AML/CFT and sanctions screening.
6. Take into account the Travel Rule for transactions via a CASP.
7. Establish a procedure for self-hosted wallets, particularly for large transfers.
8. Secure private keys and establish access controls.
9. Define a policy for converting BTC/ETH/stablecoins into EUR.
10. Maintain an audit trail: transaction hash, date, asset, amount, valuation, and donor documentation — where required.
Cryptocurrency as a new, modern channel for charity
Crypto donations and a properly structured system can offer donors what traditional bank transfers often fail to provide: global reach, 24/7 accessibility, rapid transfer of assets and the ability to verify transactions directly on the blockchain.
The best strategy for a charitable organisation is to accept cryptocurrency but not to speculate with it; to utilise the technology but not to neglect compliance; and to simplify the donation process without compromising legal accountability.
18 Stolen Bitcoins, or Why You Shouldn’t Take a Photo of Your Seed Phrase
Revolut data breach: are hackers blackmailing customers, and are their passports, IBANs and Bitcoin transactions at risk?
Trump’s crypto profits of around 2.5 billion versus investors’ losses of nearly 5 billion: has politics become part of the business model?
Crypto trader hits the jackpot, turning $1,491 into $1.2 million in 7 hours
The price of 1 Bitcoin is set to exceed $100,000. When will this happen?